September 23, 2026
Nvidia forecast 70% fiscal 2028 growth. The valuation gap is the real work.
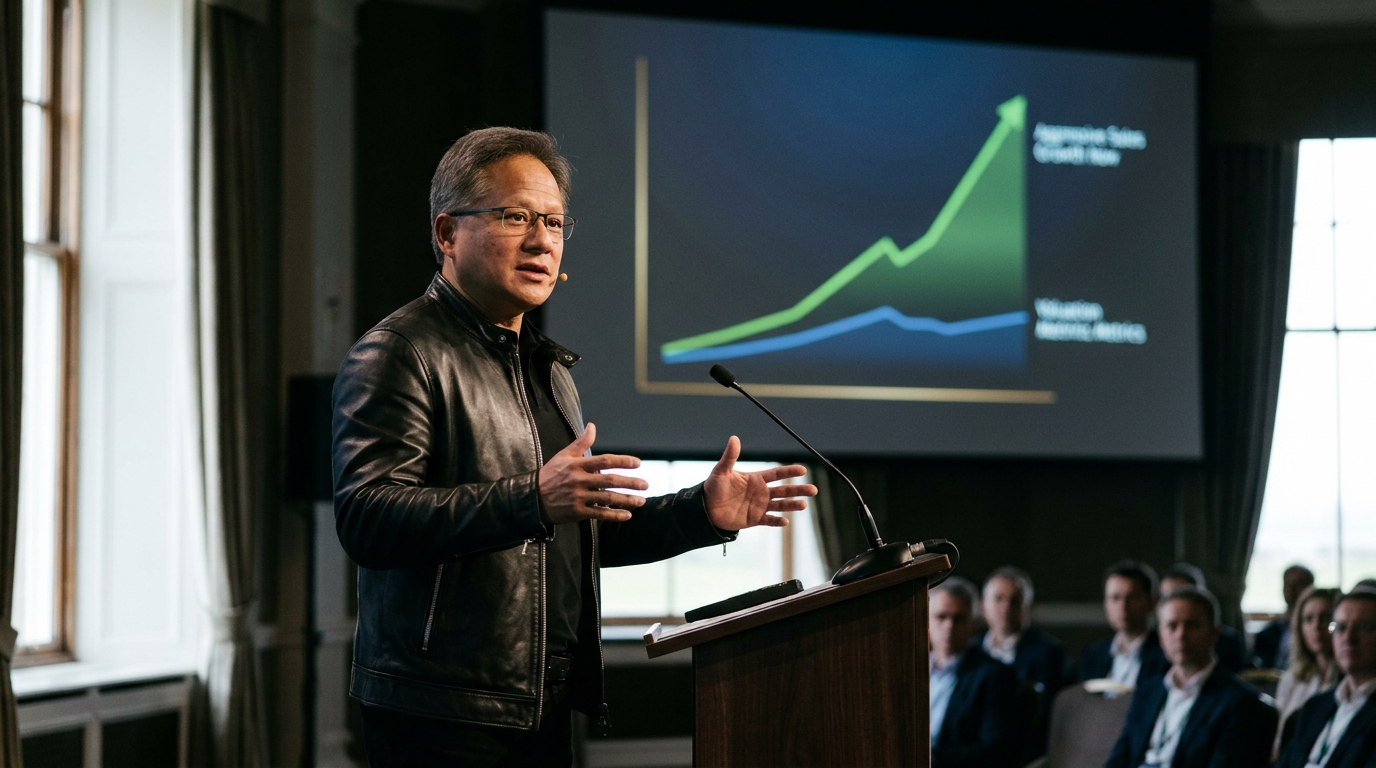
Jensen Huang stood before an audience at a King Charles-hosted AI gathering in Scotland this month and made the most explicit volume commitment of his career: Nvidia expects to sell twice as many chips in 2027 as it does in 2026. No hedge, no qualifier. Just a doubling.
Iran War TRUTH: What Was Revealed Behind Closed Doors
There’s a strategy behind the Iran war.
I know because I heard it directly in a closed-door meeting with a source whose connections run deep into global power networks.
He walked me through the real purpose and the massive deal tied to it.
The stock moved higher on the news and then mostly went back to doing what it has done for months: trade at a significant discount to where almost everyone’s earnings model says it should be.
A Multiple That Doesn’t Match the Numbers
Nvidia’s forward price-to-earnings ratio has been cited around 18, but that figure moves with the day and the data source, and it is safer to say the stock is trading in the high teens to 20s on forward earnings. Its trailing P/E has also swung widely over the past year as earnings exploded, so treating a single “12-month average trailing P/E” as a precise anchor is shaky. What is not shaky is the operating reality: Nvidia reported fiscal second-quarter revenue of $96.2 billion, up 106% year over year, with Data Center revenue up 117% to $89.0 billion. A company growing that fast is being valued like a business whose best days are already filed away.
The disconnect is not subtle. Nvidia has lagged portions of the broader semiconductor complex at times despite strong fundamentals, creating a valuation gap that has drawn attention from active managers. The question is whether that gap is an opportunity or a warning the market is sending for good reason.
Why Huang’s Forecast Should Not Be Dismissed
Cash From Oil in Days. Not Years.
No stocks. No waiting years for a payoff. A former hedge fund manager has a strategy that can turn an oil move into cash in a matter of days, and the chances come up again and again. He calls it “Oil Skimming.” And he’s giving away the entire three-step system for free.
The doubling call is not speculative. Huang echoed what management already told investors on the August 26, 2026 earnings call, where CFO Colette Kress said customers’ forecasts pointed to Nvidia’s growth doubling next year and framed the fiscal 2028 outlook, which calls for roughly 70% revenue growth, as “supply-constrained.”
Supply-constrained means demand is even larger than what Nvidia can deliver. But the more specific claims about fiscal 2028 consensus EPS jumping from $13 to $16 in 90 days, and “39 upward revisions and zero cuts,” are not figures I could verify cleanly and should be treated as directional rather than exact.
The platform driving those estimates is Vera Rubin. On the August 26 call, Nvidia described a revenue opportunity per gigawatt of roughly $40 billion for Vera Rubin versus roughly $25 billion for Grace Blackwell. CoreWeave has said it brought up a multi-rack Vera Rubin NVL72 cluster. Nvidia has also listed Nebius among partners around Vera Rubin systems. AWS, meanwhile, says it plans to deploy 2 million additional Nvidia GPUs across its infrastructure in 2027 and 2028.
The Bear Case Has Real Weight Too
The market is not wrong to apply skepticism. The structural concern is that hyperscalers are building their way out of GPU dependency. Several major AI companies, including Alphabet and Meta, have been developing in-house accelerators, and Broadcom has been explicit that its custom silicon business is a major beneficiary of that shift. In late 2024, Broadcom CEO Hock Tan predicted AI revenues in the $60 billion to $90 billion range for fiscal 2027, and more recently he has talked about AI semiconductor revenue around $115 billion in fiscal 2027.
Ex-CIA Insider Releases Trump Mid-Term Bombshell
Former advisor to the CIA, the Pentagon and the White House Jim Rickards just dropped this Trump election bombshell.
For the sake of our country, long term…
I hope he’s right.
But it could get ugly in the next few weeks.
Jim correctly predicted the Great Recession of 2008, Trump’s 2016 and 2024 election, and the Covid Crisis.
Click here to see the details because if he’s right, you need to prepare now.
Gross margin pressure adds another layer. Nvidia guided third-quarter gross margin around 74% on the August 26 call, and selling twice as many chips does not necessarily mean revenue will double, since product mix, pricing, and the platform transition between Blackwell and Vera Rubin all affect how shipment growth converts to sales.
Where to Look
For investors trying to position around this argument, five names matter most. NVDA is the central holding: if the forward multiple is genuinely in the high teens to 20s while management is still talking about roughly 70% fiscal 2028 revenue growth in a supply-constrained environment, the risk-reward compresses sharply if margins stabilize even modestly. AVGO benefits directly from the custom silicon shift; Broadcom co-designs accelerators for the hyperscalers who are reducing GPU exposure. TSM manufactures Nvidia’s chips and sits at the physical bottleneck in every scenario. AMD is the second-mover that gains most if Nvidia’s pricing power softens as competition grows. And ARM participates across hyperscaler processors and other chip architectures simultaneously, making it structurally positioned to benefit regardless of which silicon design wins the next cycle.
The Wealth Takeaway
The market appears to be doing two contradictory things at once: discounting Nvidia’s earnings while not fully pricing the risk that the bear case is wrong. A supply-constrained doubling, confirmed by the CFO and reinforced by the CEO in Scotland, is not the language of a company heading into cyclical decline. It is the language of a company that cannot build fast enough. Investors who wait for the multiple to make sense on its own may be waiting until the gap has already closed.