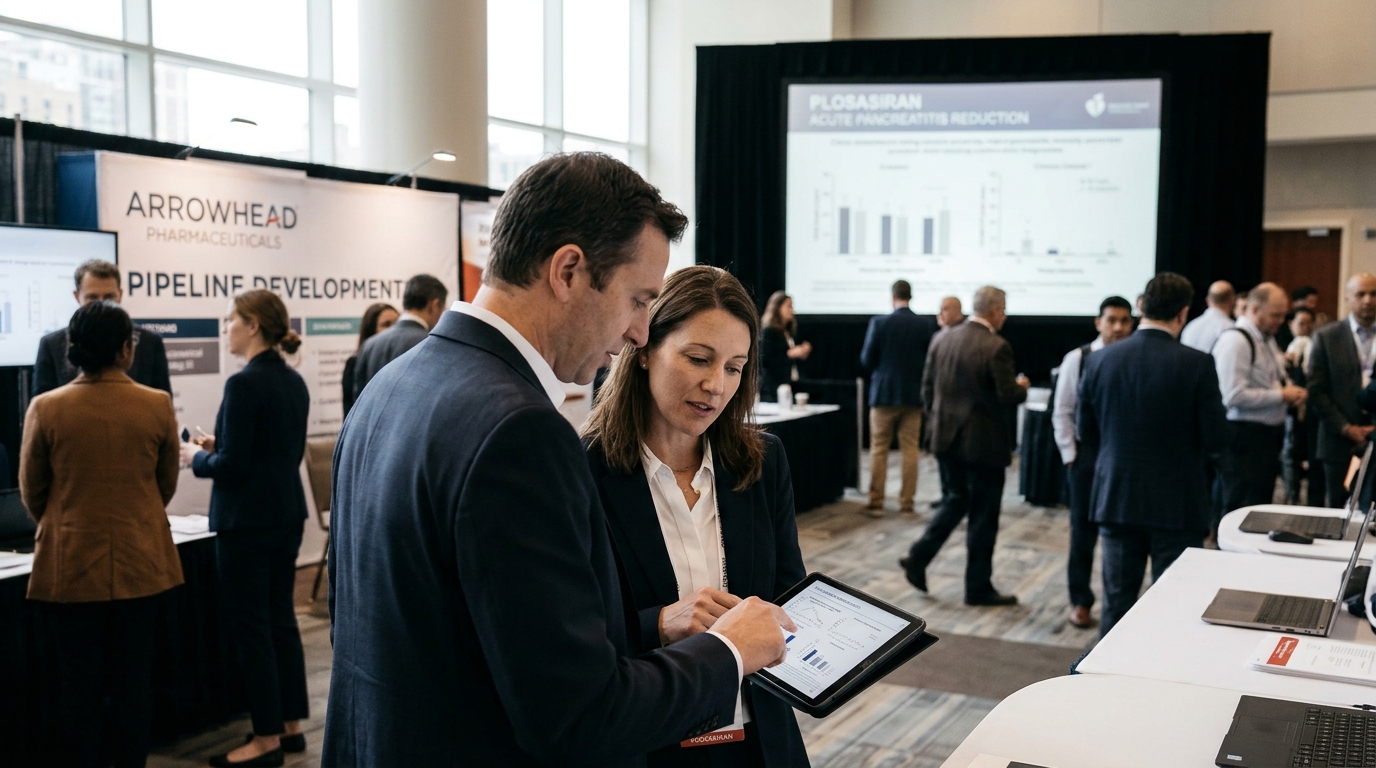
Two days before Arrowhead Pharmaceuticals reports fiscal Q4 2026 results, the company walked into the American Heart Association’s Scientific Sessions in Chicago and presented the data that may define its next five years.
At the AHA meeting, Arrowhead released new clinical data for both plozasiran and ARO-DIMER-PA, with plozasiran showing reductions in acute pancreatitis events in severe hypertriglyceridemia patients alongside lower triglyceride levels. The headline figure investors should sit with: plozasiran reduced acute pancreatitis event rates by 78% overall and 91% in severe hypertriglyceridemia patients with a recent history of acute pancreatitis versus placebo.
That is not a subtle signal. Pancreatitis reduction is the clinical endpoint that separates a lipid-lowering drug from something physicians actually reach for in high-risk patients. Through 24 months of an open-label extension, representing up to 36 months of total treatment, median reductions from baseline were 76% for triglycerides and 89% for APOC3. Durability of effect at that magnitude is rare in cardiovascular medicine.
The Regulatory Clock Is Running
The AHA data lands at a precise moment in Arrowhead’s regulatory timeline. The FDA granted plozasiran entry in the STAR pilot program for its upcoming supplemental new drug application in severe hypertriglyceridemia, and Arrowhead says it is on schedule to submit the sNDA by year-end 2026. Arrowhead has also said it believes the submission could qualify for a six-month Priority Review, which would allow the company to retain its Priority Review Voucher for another use or monetization.
Meanwhile, Arrowhead completed enrollment in the global Phase 3 YOSEMITE trial of zodasiran for homozygous familial hypercholesterolemia, a rare genetic condition that causes severely elevated LDL cholesterol and early-onset cardiovascular disease. YOSEMITE completion is guided to mid-2027. That means a second cardiovascular approval could follow plozasiran within two years.
The cardiovascular pipeline is not the only place where gene-silencing biology is converging with aging-related disease. GLP-1 receptor agonists are now generating clinical data across metabolic, cardiovascular, and kidney disease in the same patient populations Arrowhead is targeting.
What Thursday’s Earnings Actually Tell You
Arrowhead releases Q4 2026 results after the close on November 12. Analysts expect a loss of $1.52 per share on revenue of $61.18 million. The loss is not the story. In the prior quarter, Arrowhead missed EPS estimates but generated $75.25 million in revenue against analyst expectations of $44.17 million. Commercial momentum from REDEMPLO and partnership milestones have repeatedly outrun Wall Street’s model.
Arrowhead’s TRiM platform can silence genes across liver, lung, muscle, adipose, and central nervous system tissue, which matters because the cardiovascular pipeline is not the ceiling. It is the proof-of-concept for a platform that can extend into obesity, neuromuscular, and pulmonary disease.
The Risk That Deserves Honest Attention
Safety signals, including glycemic and hepatic findings, raise the risk that heavy R&D spending on these late-stage programs might not convert into durable product income if tolerability questions grow. The company has recently reported total debt to equity of about 270%, and recent filings show sizable net losses over the past year. An sNDA delay or an unexpected FDA question letter would be painful at that leverage level.
The severe hypertriglyceridemia market was internally estimated at $3 to $4 billion before SHASTA-3 and SHASTA-4 posted these pancreatitis numbers. After them, that estimate looks conservative. Thursday’s call will tell investors how management is thinking about the commercial build. The pipeline data already made the case.