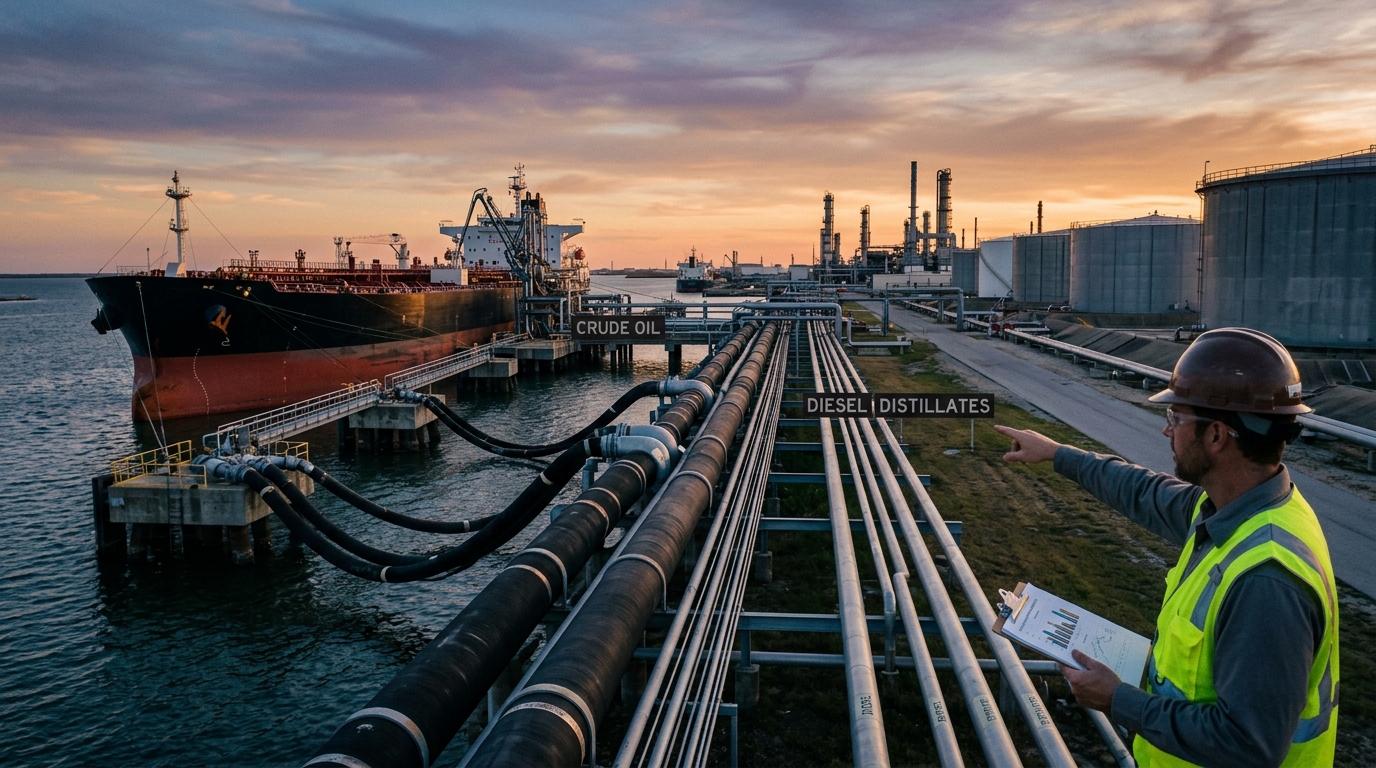
Most investors are watching crude prices. That is the wrong variable. Brent has oscillated between roughly $85 and $107 since late July, and Goldman Sachs said Sept. 30 that Persian Gulf oil exports have recovered to around their 2025 average. Gulf oil exports reached 23.3 million barrels per day in the latest week in September, with crude shipments recovering to 108% of their 2025 average. Key refined products including diesel and jet fuel, however, remain far lower amid refinery outages and shipping risks.
That divergence is the investment story. JPMorgan’s head of global commodities strategy, Natasha Kaneva, put it plainly: “the crude market has largely normalized even as refined product supplies remain constrained.” Despite the crude rebound, refined product shipments moving through Hormuz remain well below pre-war levels, averaging 677,000 barrels per day against 3.6 million before the war, according to Kpler. The gap between what the well-supplied crude market implies and what the product market is actually delivering is where the refining premium lives.
Why the Refinery Damage Is Structural, Not Temporary
Infrastructure damage to refineries in the Middle East has kept outages elevated, so the region is simply making less finished product. That is not a shipping problem diplomacy resolves overnight. Kpler expects Middle Eastern refined-product exports to require another three to four months to recover as refineries return to stable operating rates and rebuild export flows. Layered on top: intensifying Ukrainian attacks on Russian refineries and export infrastructure have further tightened product markets, with both exports and domestic fuel deliveries impacted.
The result is a crack spread environment without modern precedent. Distillate inventories are running well below seasonal norms, retail diesel reached $5.85 in early September against the prior record of $5.8159 from June 2022, and U.S. refineries ran at about 98% of operable capacity. Before this crisis, the diesel crack margin typically ran $15 to $30 per barrel. Bloomberg reported the U.S. diesel crack cleared $100 per barrel for the first time and peaked above $106.
Where the Cash Is Going
The beneficiaries are domestic refiners with Atlantic Basin exposure and access to cheaper domestic feedstocks. Marathon Petroleum, Valero, and Phillips 66 generated a combined $12.6 billion in profits in the second quarter of 2026. The SEC filings are unambiguous on causation. Marathon’s Refining and Marketing adjusted EBITDA was $24.84 per barrel in Q2 2026, versus $6.79 per barrel in Q2 2025, with margin per barrel rising to $36.33 from $17.58, primarily due to higher crack spreads. Valero’s filings describe results benefiting from strong global demand for transportation fuels amid constrained worldwide supply as geopolitical developments further limited refining capacity.
Shares have reflected this. Refiners have posted steep gains in 2026 alongside the surge in global refining margins. Yet analyst 12-month price targets are trailing current share prices, suggesting equity markets are pricing in continued margin strength faster than Wall Street models.
The Risk Most Buyers Are Underpricing
The simple version of the bull case assumes the product gap persists indefinitely. It will not. A ceasefire that lowers Brent by fifteen dollars could initially widen the crack rather than close it, at least temporarily, because it would free up crude for processing before Gulf and Russian refineries fully restart. That paradox is real and useful to own in the short run.
But Middle Eastern facilities will restart, Russian plants may recover part of their lost production, and the IEA has forecast global refinery runs to contract by about 2 million barrels per day in 2026 before rebounding 3.1 million barrels per day in 2027. The question is not whether margins compress, it is whether they compress before or after Q3 earnings catalysts land. Phillips 66, Marathon, and Valero have signaled strong earnings power when crack spreads stay elevated, and the market is treating that as a through-year-end condition. With distillate stocks at record seasonal lows and Gulf product exports still far below pre-war volumes, the ceiling on this trade is diplomatic and mechanical, not market-driven. Until either changes, the spread is real.