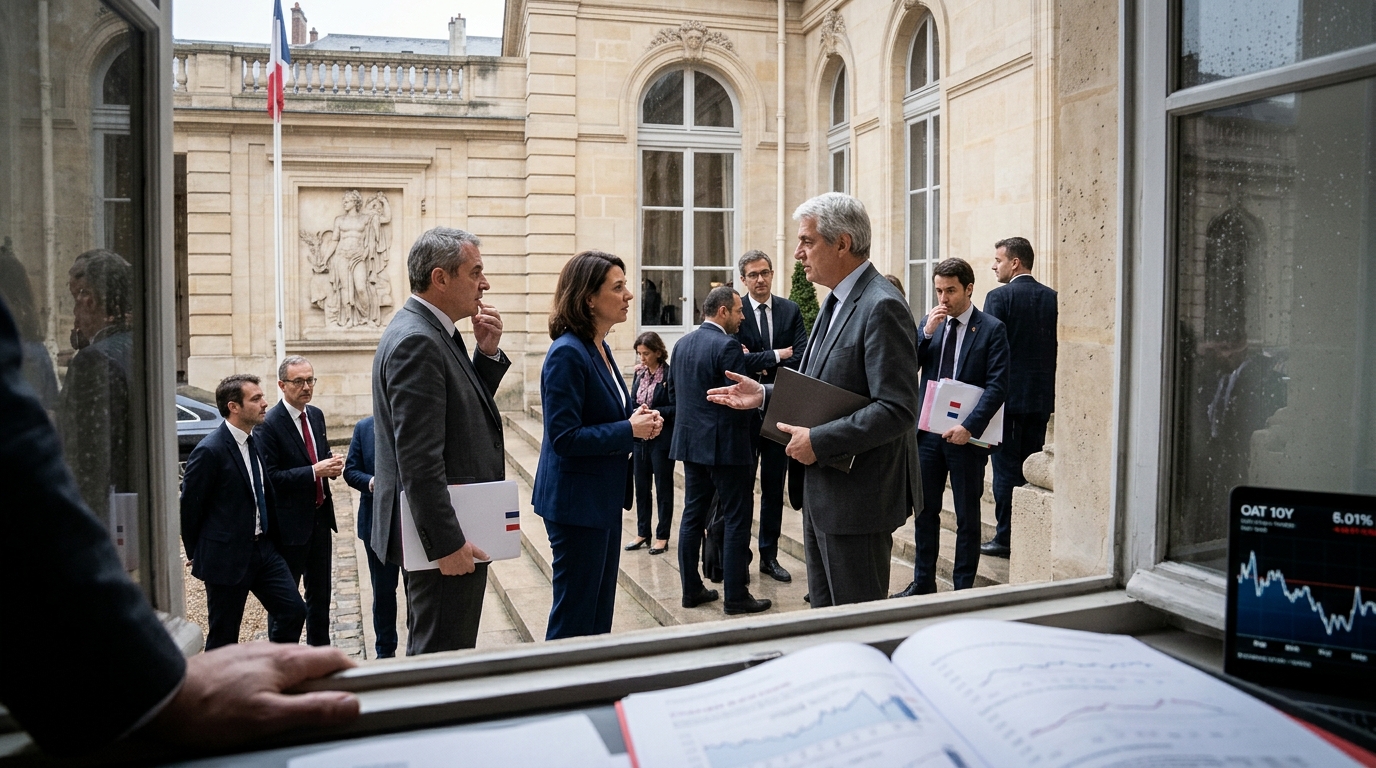
The number that matters right now is not the CAC 40. It is the spread between French and German government bonds, which has escalated to around 160 basis points, its highest level since the euro-area sovereign-debt crisis era.
French government borrowing costs spiked on Wednesday, with the yield on the benchmark 10-year OAT surpassing 5% for the first time since 2002. The move was brief and the threshold was crossed.
To appreciate how badly France has underperformed, consider the context. Since the Hormuz crisis began, 10-year OAT yields have risen about 150 basis points, compared with about 115 basis points for Treasuries, 132 basis points for Italian bonds, and about 83 basis points for German Bunds. That is not a global sell-off punishing France equally. It is a global sell-off punishing France disproportionately. The French 10-year OAT yields 4.99%, versus 3.41% for the German Bund as of October 21. France now sits between Germany and the U.S. on yield, but without the reserve-currency status of one or the growth trajectory of either.
What the Market May Be Missing
The political dimension compounds the fiscal one. The French government is struggling to pass a budget through a divided parliament as market pressure for significant fiscal consolidation mounts in response to a swelling national debt and wide deficit. A vote on the taxation side of the bill has been pushed back to October 27 because a large number of amendments still need to be discussed. Budget Minister David Amiel has warned that amendments already approved would worsen the budget deficit by €10 billion.
The baseline most analysts expect is messy but not catastrophic. Allianz Trade expects a budget by year-end through ordinances or Article 49.3, keeping the 2027 deficit at around 5.3% of GDP, which should contain fiscal slippage and stabilize OAT spreads in the 120 to 150 basis point range. That is a meaningful compression from current levels, but it requires the government to act, and that is the part the bond market is not taking on faith.
What investors may be underweighting: the rating calendar. Moody’s currently rates France Aa3 with a negative outlook and is scheduled to review that rating on October 23, which is tomorrow. A Moody’s downgrade this week, ahead of the October 27 budget debate, would land at the worst possible moment for sentiment.
Where It Shows Up
The sovereign pressure runs directly through the French banking sector. French banks hold large amounts of OATs, and when yields rise, the value of those bonds falls while funding costs can also rise. That relationship showed up clearly in August: Reuters reported BNP Paribas fell about 4%, Société Générale lost about 3.6%, and Crédit Agricole dropped about 3.3% on August 27 on French budget fears. BNP Paribas third-quarter results are due October 28, the day after the Assembly vote. Investors in BNP, GLE, and ACA face a compressed sequence: a budget vote, a potential rating action, and earnings, all within six days.
Risks and Counterpoints
Long-term investors are sitting out ahead of the elections, given budget uncertainty and the sensitivity of OATs to political fragility. That positioning itself creates an asymmetric opportunity if the budget passes in any form: a relief rally in spreads would likely be sharp. The bearish case is that since a 2024 snap legislative election produced a hung parliament, successive minority governments have leaned on Article 49.3 to force through budgets, and if no budget passes within 70 days and the government does not invoke that power, it could pass an emergency law rolling over the 2026 budget. Rolling over last year’s numbers does nothing for a deficit already running at 5.4% of GDP. It just buys time the bond market has already stopped offering at a discount.
What to Watch Next
Three dates define the next week. Moody’s publishes its France review on October 23. The Assembly resumes its budget debate on October 27. BNP Paribas reports earnings on October 28. The ECB policy decision follows on October 29. Any one of those events can move OAT spreads meaningfully. All four landing in sequence make this the most consequential stretch for French assets since the spring.