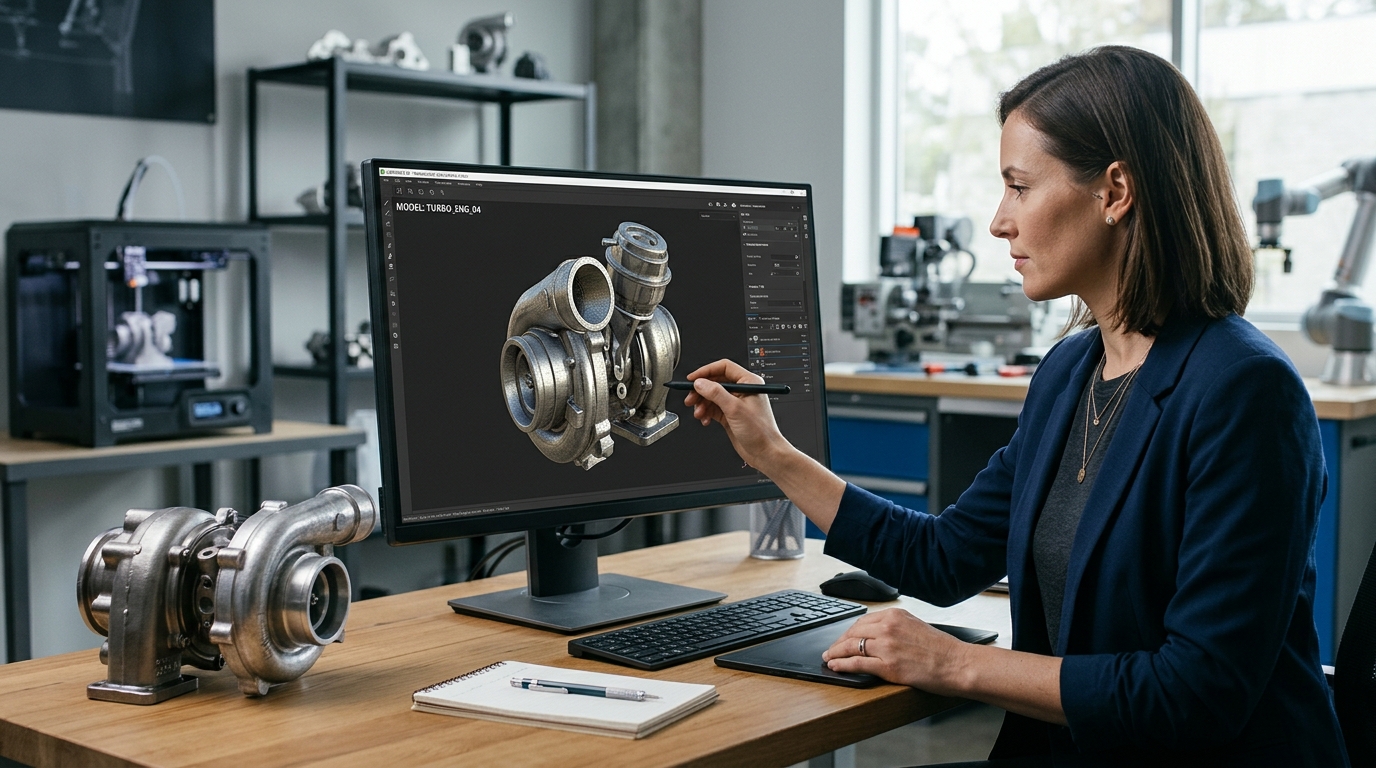
Most investors still think of Adobe as a Photoshop and PDF company. That reading is costing them a more interesting story. Adobe has increasingly pushed its Substance 3D tools into manufacturing and product-design workflows, including automotive and industrial use cases for photorealistic visualization and digital-twin style content creation. That is not just a marketing campaign. It is a real insertion into design and content pipelines that once belonged exclusively to Autodesk and Siemens.
Adobe’s Firefly generative AI is integrated into Substance 3D Sampler and Stager, speeding up texturing and staging work for industrial designers, game developers, and VFX professionals. One capability that helps in manufacturing-adjacent visualization is material creation from photography: Substance 3D Sampler can turn real-world images into PBR materials and generate maps such as normal, height, metallic, and roughness, which is useful when physical materials need to be reproduced in 3D for visualization or AR and VR use.
The numbers behind this push are notable. In Adobe’s Q3 FY2026 materials, the company said AI-first ending ARR exceeded $650 million and grew more than 150% year over year. Adobe also said Firefly ending ARR grew 40% quarter over quarter across the Firefly app and credit packs. Neither figure is driven by individual creative subscriptions alone, and Adobe has been positioning these offerings for enterprise use cases.
The productivity case is real, but the headline numbers get slippery once you move beyond specific case studies. Subaru examples and broad claims about a “50 to 70% reduction” in concept-to-validated-design timelines are not consistently attributable to a single, verifiable source, so treat them as directional rather than universal. The better-documented reference point is the broader generative design ecosystem: General Motors worked with Autodesk on a generative-design seat bracket that consolidated eight parts into one, and Autodesk has described the result as 40% lighter and 20% stronger than the prior design. Adobe is not the only tool in these workflows, but its Substance layer can be where physical material look-and-feel becomes a reusable digital asset that feeds downstream visualization and content production.
What makes the Adobe angle different from the Autodesk angle is the content supply chain. In industries like automotive and manufacturing, imagery often has to stay grounded in physical truth, reflecting geometry, materials, and variants. Adobe and NVIDIA have described a joint effort around a cloud-native 3D digital twin workflow for marketing, built on NVIDIA Omniverse libraries, with the goal of letting marketing and product teams work in parallel before physical manufacturing begins. That collaboration positions Adobe closer to industrial operations than a simple downstream “make it look pretty” role.
Adobe is not the only software company repositioning around physical infrastructure workflows. Autodesk’s construction and manufacturing platform is running on the same macro tailwind — and the market punished that stock on a beat too.
What Investors Are Pricing Incorrectly
The market still values Adobe primarily on its Creative Cloud subscriber base and PDF monetization. In Q3 FY2026, Adobe reported subscription revenue for Creative and Marketing Professionals of $4.65 billion, with growth described as 12% year over year in its prepared materials. That is the line analysts watch. But the faster-moving variable is enterprise adoption of Firefly and 3D workflows, which still does not surface cleanly as its own line item.
The risk is real. Adobe competes against purpose-built CAD and generative-design tools from Autodesk, PTC, and others, and against an expanding field of text-to-CAD startups. Mature generative-design tooling is already deployed in weight reduction and additive manufacturing workflows. Adobe’s edge is its existing enterprise licensing footprint, and its positioning of Firefly as commercially safe for business use, including the company’s statements that Firefly is trained on licensed content and public-domain material, and that Adobe does not claim ownership of what customers create with Firefly. For industrial clients that need clear usage rights, that posture can matter.
Enterprise AI adoption is reshaping how the market values software businesses across the stack. Enterprise customers moving AI workloads from proof-of-concept to production are forcing a revaluation of the data and workflow platforms beneath them.
The wealth takeaway: Adobe’s 3D and manufacturing push is not yet priced into a stock the market often treats as a creative software subscription business. That gap is where the patient investor’s attention belongs.