The document that will determine how institutions price what could become the biggest IPO in history has not yet arrived. But the governance question that will dominate every investment committee meeting when it does has already been settled by the founders themselves.
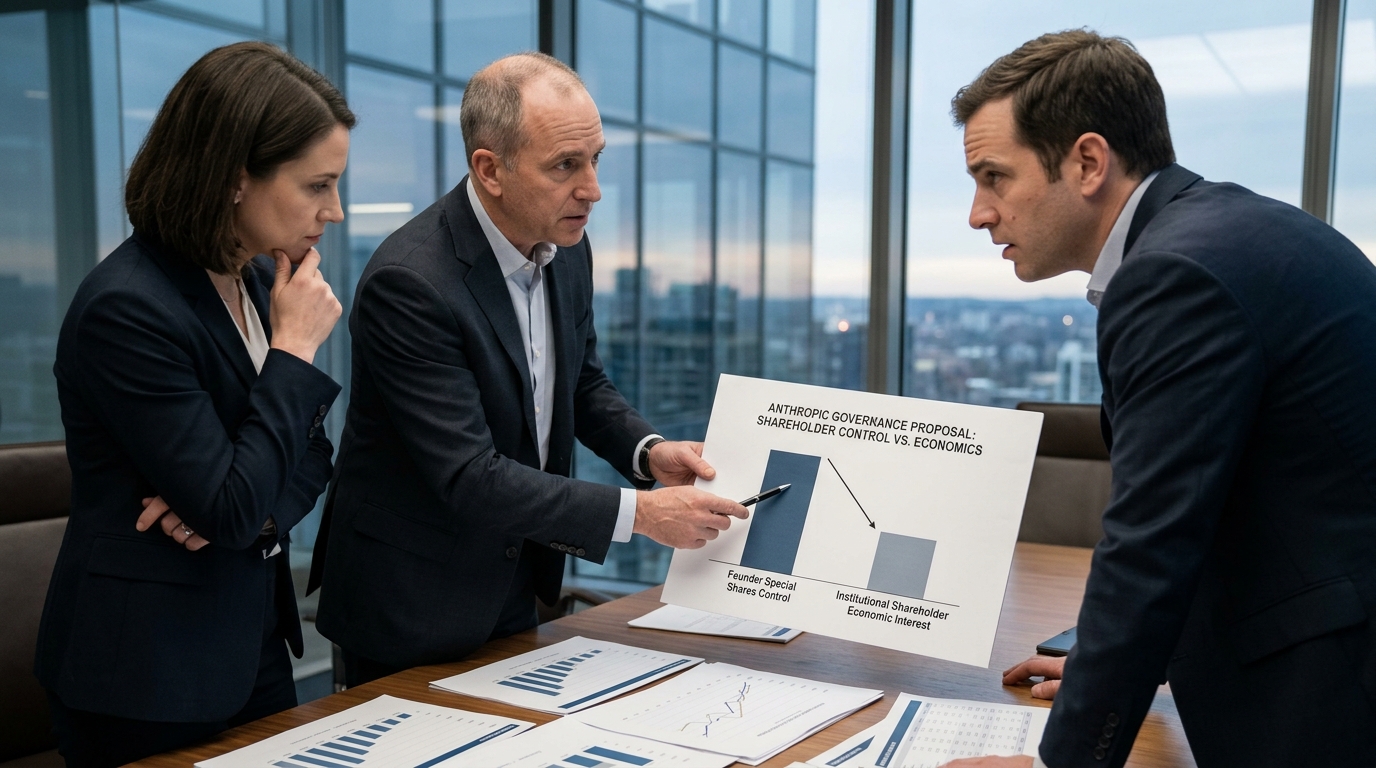
Anthropic is asking shareholders to approve a structure that would give CEO Dario Amodei and his six co-founders special shares carrying a combined 50.1% of the vote on most corporate matters, as long as at least three of them keep a minimum stake. The voting control carries no extra economic value. The vote is expected in the coming days. Investors expect the Claude maker to go public at a valuation of $2 trillion or more, which would put it on track to be the largest initial public offering in history.
The Bull Case: This Is Just How AI Looks Now
Institutional investors who push back on this structure will be arguing against a tide that has already come in. S&P Dow Jones Indices moved in 2017 to make most newly public companies with multiple share classes ineligible for inclusion in the S&P Composite 1500 and related headline indices, with grandfathering for existing constituents. Palantir joined the S&P 500 effective September 23, 2024. The index exclusion threat, the most credible weapon governance hawks once held, is weaker than it once was.
The arrangement emulates a founder-control structure at Palantir, which awards co-founders a special class of shares giving them collective voting control in most corporate matters. That worked out tolerably well for investors who held their noses and bought in anyway. Palantir is now an S&P 500 component.
The revenue trajectory makes patience easier to justify. A handful of Anthropic’s backers told the Financial Times that the Claude maker’s annualized revenue is expected to land between $100 billion and $120 billion before the year closes, representing growth of more than tenfold compared with the $47 billion annualized revenue the company said it had reached in May. At that clip, the governance discount is a second-order concern.
The Bear Case: Seven Is Not One
Palantir concentrates control in three founders with a decades-long working relationship. Anthropic’s structure distributes 50.1% across seven people, and the control would last as long as at least three of the seven keep a minimum stake. That three-founder trigger is a fault line. What happens when the group fractures over a strategic call? Who actually decides?
The shares carry no extra economic rights, so the founders would not get a bigger cut of profits or a sale, just the votes. That is meant to be reassuring. It is also the point: Dario Amodei and his co-founders want to run Anthropic on their own terms indefinitely, regardless of what Amazon, Google, or any public shareholder thinks. Anthropic has committed to spend more than $100 billion on AWS technologies over the next decade, including Amazon’s Trainium chips. Amazon is simultaneously a creditor, a cloud provider, an equity holder, and now a party with no say over the company’s direction.
What Investors Are Missing
The governance debate obscures a more important question: the special share structure is designed to keep the founders in place, but it is also intended to let founders pursue personal wealth donation goals while retaining strategic direction of the company. Anthropic operates as a public benefit corporation with a Long-Term Benefit Trust that holds a special class of stock with the power to elect and remove directors over time, and Anthropic has said Trust-appointed directors now make up a majority of the board. The Long-Term Benefit Trust would keep those board powers, but the founders would control nearly everything else.
That layering is unlike anything in the current S&P 500. Institutions buying at a $2 trillion valuation would own economic exposure without much board influence. Whether they accept that depends on how badly they need the position, not on any principle they still hold about dual-class shares.
Stocks to Watch
- Amazon (AMZN): Amazon does not disclose its ownership percentage, but Fortune reported that estimates based on its public filings put its stake somewhere in the mid-to-high teens, implying a position worth roughly $135 billion to $160 billion at Anthropic’s $965 billion valuation as of May 2026. The IPO crystallizes that gain and raises a pointed question: Amazon has no voting power over a company it has funded more heavily than any other investor.
- Alphabet (GOOGL): Court filings have indicated Google owns about 14% of Anthropic in equity, and U.S. lawmakers have described that stake as hard-capped contractually at 15%. Alphabet has also signaled plans to commit additional capital to Anthropic, but the precise total and terms have varied across reports. It, too, will be a largely non-voting shareholder in the company it helped build.
- Palantir (PLTR): The closest public comparable for founder-controlled AI infrastructure. Palantir’s multi-class governance structure has been a recurring flashpoint for governance-focused investors, even as the stock ultimately cleared index hurdles and joined the S&P 500. If Anthropic prices at $2 trillion with this structure intact, it validates every governance concession Palantir ever asked for.