For decades, memory was the semiconductor industry’s most punishing business. Prices surged, fabs were built, oversupply arrived, and shareholders absorbed the wreckage. The cycle repeated so reliably that even brilliant analysts treated it as a law of nature.
Something has changed. The question now is whether it has changed permanently.
Global DRAM revenue jumped 369% year over year in the third quarter of 2026 to just under $200 billion, Counterpoint Research reported, as demand for AI accelerators and data center servers kept supply tight and pushed selling prices to new records. The number that makes that figure meaningful is this: Counterpoint research director MS Hwang noted that DRAM prices that once sat at 20 to 30 cents per gigabit have climbed to about $2 per gigabit, with HBM4 heading toward $4 per gigabit.
What makes the revenue figure almost more striking is what did not happen. Counterpoint said bit shipments rose only about 4%. The record is chiefly a pricing story, not a comparable increase in supply. Counterpoint principal analyst Choi Jung-ku described the upcycle as “a supercycle led by prices, not shipments,” adding that AI has turned memory from a commodity into a scarce, high-value resource.
The forward view is just as striking. TrendForce said conventional DRAM contract prices are projected to rise another 10% to 15% quarter over quarter in Q4 2026. NAND flash contract prices are forecast to climb 15% to 20% over the same period.
Beyond Q4, the supply picture grows tighter still. SK hynix told investors on October 28 that its DRAM and HBM output is effectively sold out through 2029, with customer demand more than double its supply capacity. Samsung Electronics said on October 29 that its 2027 HBM supply is sold out, with price talks concluded at target levels. SK hynix CEO Kwak Noh-Jung said in a Reuters interview published July 10, 2026 that 2027 would be the worst year in the memory industry’s history for supply, with demand projected to outstrip supply beyond 2030.
Nvidia’s anxiety about supply is visible even in unconfirmed reports. The Information reported on November 6 that TSMC had begun drawing up plans for 3D DRAM at Nvidia’s request. TSMC publicly pushed back, saying it is a pure-play logic foundry and plans to remain one. Even major memory makers are years away from 3D DRAM, so pursuing it would not address shortages for at least five years. The denial matters less than what prompted the story: Nvidia is worried enough about memory to explore every option available.
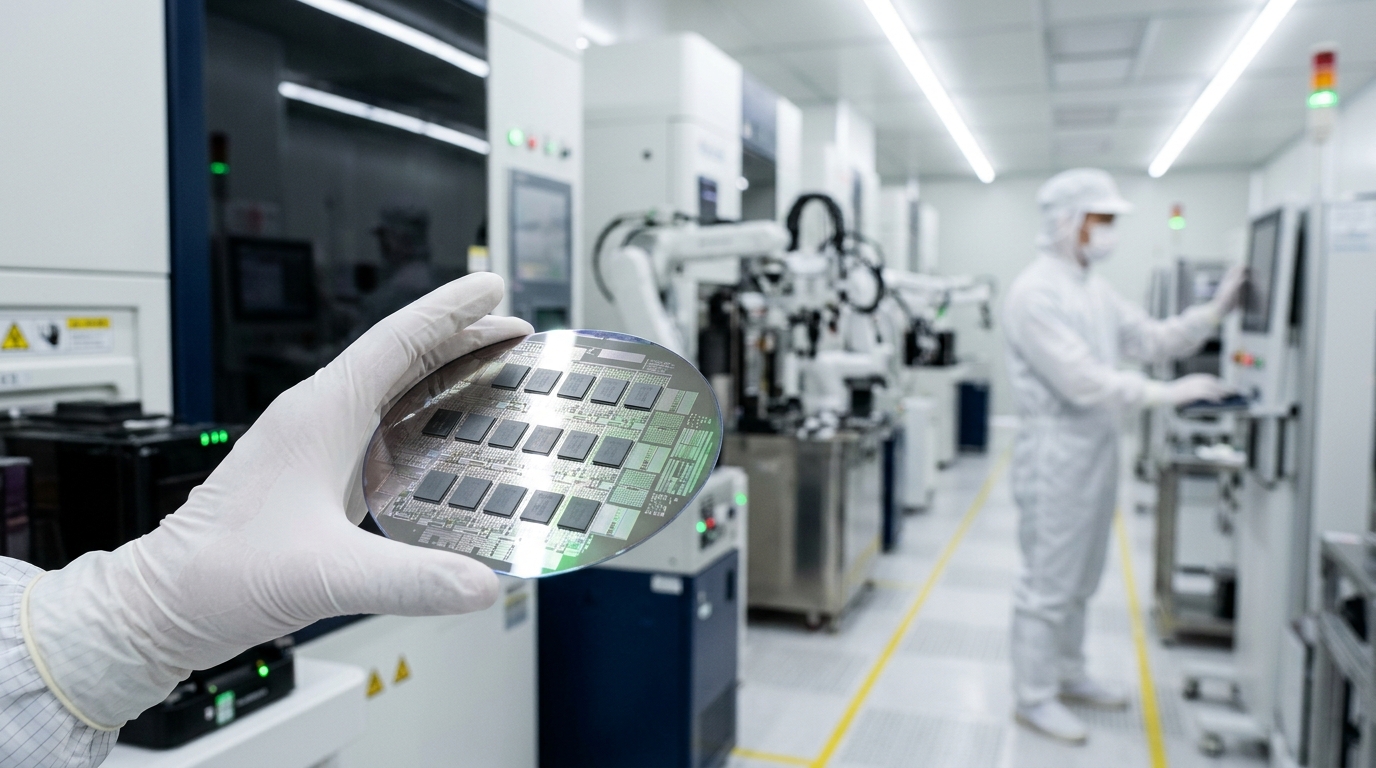
For investors trying to think beyond the next quarter, the structural case rests on three companies: Samsung, with 38% of Q3 DRAM revenue; SK hynix, with DRAM and HBM output effectively sold out through 2029; and Micron, the most accessible pure-play for US investors. Major manufacturers like Micron, Samsung, and SK hynix continue to divert production capacity toward high-margin HBM and enterprise solutions, effectively rationing the supply that everyone else needs.
The honest risk is the one that has burned memory investors before. Memory cycles bite. Anyone who has watched Samsung, SK hynix, or Micron for more than one boom knows that today’s shortage can become tomorrow’s glut if demand slows after capacity finally arrives. Fabs announced today do not reach real volume for years, so even a sudden slowdown in AI demand might not show up as looser memory supply until later in the decade.
That delay is precisely the point. The window between when capacity is ordered and when it reliably arrives has never been wider, and the buyer on the other side of these contracts is not a PC maker negotiating on margin. It is Nvidia, Microsoft, and Google, competing to secure the one component that limits how many AI servers they can build. That is a different market than the one that destroyed memory returns for thirty years. Whether it stays different is the only question that matters.