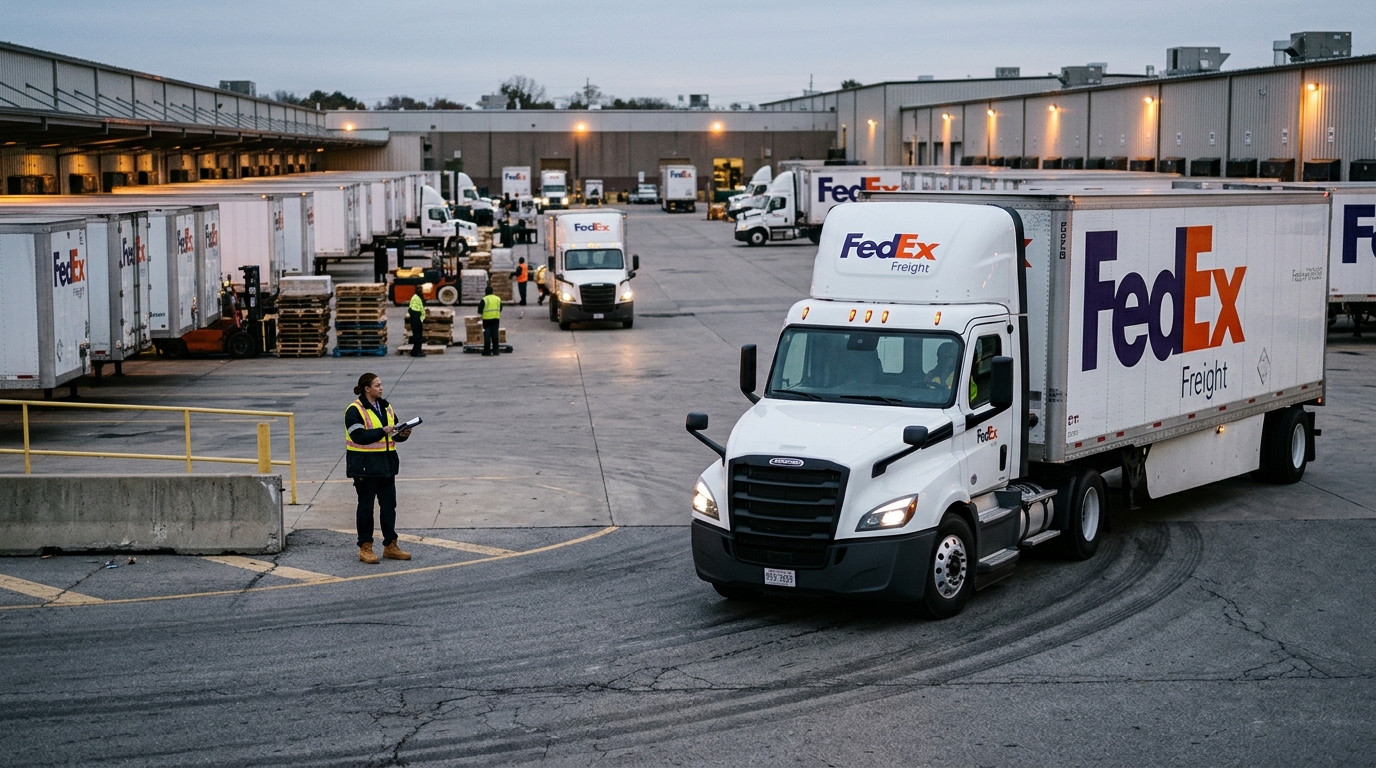
When FedEx completed its separation of FedEx Freight on June 1, the market cheered the concept. Five months later, both stocks are asking investors to be patient.
The spinoff established FedEx Freight Holding Company, Inc. (NYSE: FDXF) as an independent, publicly traded leader in the North American less-than-truckload industry. In connection with the separation, FedEx Freight paid a cash dividend of approximately $4.1 billion to FedEx, funded through a $3.7 billion senior notes offering completed in February 2026 and borrowings under a delayed-draw term loan facility. That cash infusion was real. The margin expansion that was supposed to follow is still pending.
FedEx Freight generated $8.795 billion of revenue in fiscal 2026, and reported $1.1 billion of adjusted operating income, implying an adjusted operating margin of roughly 12.6%. That is respectable, but it falls well short of the best-in-class LTL operators. FedEx Freight has said it is targeting 15% medium-term adjusted operating margins, though historical performance and near-term cyclical troughs raise questions about sustaining those levels through the full cycle.
In its first official quarterly earnings report as a standalone public company, FedEx Freight delivered results that topped Wall Street expectations and offered encouraging commentary on self-help improvements. CEO John Smith noted that since June 1, the company renewed approximately 25% of its contractual portfolio and achieved its strongest renewal pricing performance in recent years. That is tangible progress. It has not been enough to hold the stock up.
The parent company is a different kind of puzzle. FedEx shares fell more than 5% after-hours following its first quarterly report post-spinoff, as forward guidance disappointed Wall Street despite strong headline numbers. The stripped-down FDX is now a pure-play air and ground parcel network, and investors are still recalibrating what that is worth on a standalone basis.
The cost story, at least, is substantive. FedEx has said it achieved over $1 billion in transformation-related savings in fiscal 2026, with financial results reflecting structural cost reductions from DRIVE, its comprehensive program to improve long-term profitability. The company has said it expects to achieve nearly $1 billion of Network 2.0 and associated initiatives savings by the end of calendar year 2026. FedEx has also said DRIVE delivered structural cost savings in excess of management’s publicly announced targets.
A sum-of-the-parts analysis suggests the current FDX price already reflects optimistic outcomes for both the remaining company and the spinoff, leaving limited upside unless both units outperform. That is the core tension for investors right now. The logic of the separation is sound: a focused LTL carrier runs leaner than one buried inside a global logistics conglomerate. But sound logic does not pay dividends. Recent analyst price targets for FDXF cluster in the mid-$140s on average, implying mid-teens upside from early November levels, contingent entirely on the company translating its pricing wins into durable margin improvement. Watch for the next standalone results. That is where the proof arrives or it does not.