There is a category of earnings event that experienced shipping investors call a sell signal disguised as good news. Maersk delivered one this morning.
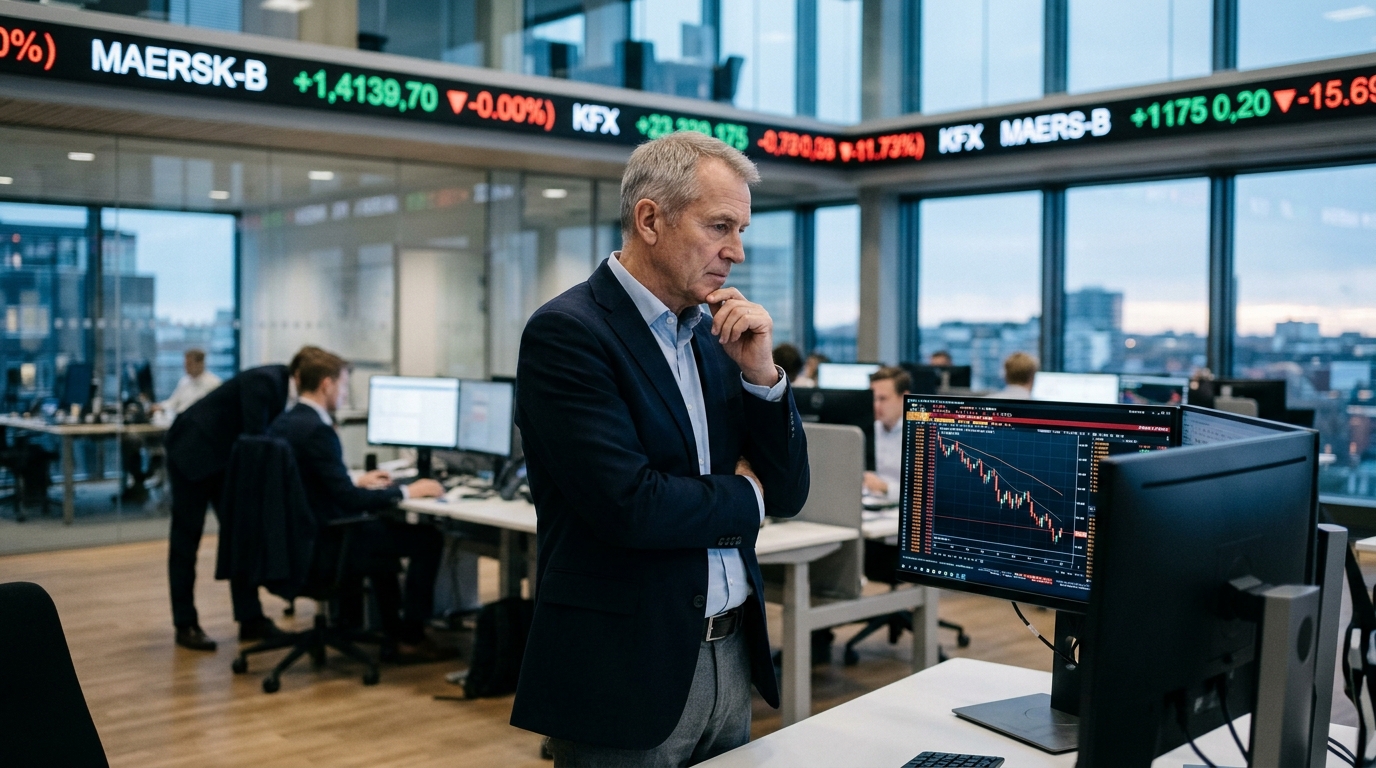
The Danish shipping group raised its 2026 guidance again on Thursday as port congestion and AI-related industrial cargo flows kept container freight rates high, but the stock still fell about 11% as the market focused on what comes next rather than what just happened. The average loaded freight rate rose about 46% year on year to $3,287 per forty-foot equivalent unit. On its face, that combination of earnings, rate strength and an upgraded outlook should be a catalyst for the stock. Instead, Maersk shares fell as much as 11.6%.
Why the Upgrade Was Already Priced In
Maersk’s third-quarter update included a sharp uplift in full-year targets, lifting its underlying EBIT outlook to $8-$8.5 billion from a prior range of $4.5-$6.5 billion and raising its EBITDA guidance to $14-$14.5 billion, while Q3 group revenues climbed to $18.1 billion. Yet the quarter still landed below some expectations, which mattered because investors were already conditioned to assume strong conditions.
The sell-off was also still being read through the lens of the late-October Goldman Sachs downgrade, which cut Maersk to Sell from Neutral with a DKK 18,000 price target, arguing that near-term earnings were backward-looking and unlikely to sustain the share price as underlying freight rate trends began to soften. Goldman’s reasoning cuts to the heart of how institutional investors read this sector: a guidance raise that merely meets consensus is not new information, it is confirmation that the market was already right.
The Core Tension: Rates Built on Sand
The jump in profit guidance came from higher prices rather than more cargo, leaving Maersk’s earnings tied to congestion and disruption that some analysts expect to fade as ships return to the Suez route and new vessels arrive. Ocean volumes were largely unchanged from a year earlier, while freight rates rose about 46% year on year. That is not a volume story. It is a congestion story, and congestion resolves.
Goldman’s analysts had warned that the stock was already pricing in a medium-term EBITDA scenario of roughly $14 billion annually, precisely the level Maersk’s new guidance now targets, and that container market oversupply through 2027-2029 made that scenario difficult to sustain. The supply math is not subtle. Container vessel capacity is forecast to grow 4.6% in 2026 and 9% in 2027. Accelerated fleet growth, warns BIMCO Chief Shipping Analyst Niels Rasmussen, could weaken the supply/demand balance in 2027.
What Investors Are Missing
The debate is framed as a question about when rates fall. The more interesting question is why Maersk itself is accelerating into the cycle. The company has confirmed orders for 26 large container vessels placed in September, a move that has been widely described as a strategic pivot back toward ordering capacity after years of emphasizing integrated logistics. Some industry trackers have put Maersk’s order book at 131 vessels. Management is signaling, with capital, that it expects demand structural enough to absorb capacity. The market is not convinced those two views can both be right.
Drewry expects further pressure on transpacific rates as U.S. ocean import volumes are forecast by the National Retail Federation to decline 11% month on month in November. That is the number that matters for how Q4 guidance shapes up, and it points squarely at a softer sequential result.
Stocks to Watch
Maersk (MAERSK-B): The stock is now a referendum on whether $14 billion EBITDA is a floor or a ceiling going into 2027.
Hapag-Lloyd: The Hamburg-based carrier now expects group EBITDA of $3.9 billion to $4.4 billion for 2026, up from a previous range of $2.7 billion to $3.7 billion. Its pending acquisition of ZIM adds an M&A variable on top of an already uncertain rate cycle.
ZIM: The highest-beta name in the group. ZIM now expects adjusted EBITDA of between $2.7 billion and $3.0 billion for the year, up from a previous forecast of $2.0 billion to $2.4 billion. Its heavy transpacific exposure means it captures rate upside fastest and loses it fastest. If November’s import decline lands as Drewry projects, ZIM is where it shows up first.